Family Costs
Supporting adult children while funding your own retirement
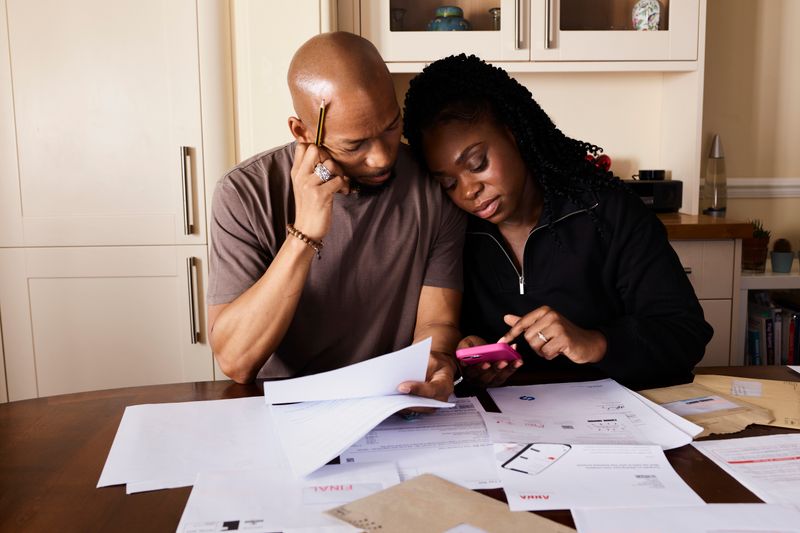
Both demands land in the same decade, and the money given cannot be recovered later. Naming a limit in advance is the only mechanism that works.
Most explanations of financial support for adult children stop at the point where it starts to matter. This one carries on.
The short version
- Money given from retirement provision cannot be replaced, because the contributing years are ending.
- Open-ended support is harder to withdraw than a defined amount.
- A gift, a loan and an investment are different things and should be labelled at the time.
Why the timing is difficult
Adult children commonly need help with housing, study or a period of low income exactly when their parents are in their final high-earning years. Those years are when retirement provision is most productively built, because there is still time for it to grow and the income to fund it. Money moved from one to the other is not a temporary reallocation; it is a permanent transfer, because the contributing years do not repeat.
That is the honest framing, and it does not mean the transfer is wrong.
You cannot borrow for retirement
Children can generally borrow for study, for property and for a slow start; parents cannot borrow to fund retirement. This asymmetry is the strongest general argument for a parent protecting their own provision before giving.
A parent who runs short later may become dependent on the same children, which converts a gift into a longer-term cost for everyone. Saying this out loud to adult children is uncomfortable and usually better received than parents expect.
Decide the amount before the request
Support that begins as a temporary arrangement and continues indefinitely is the pattern that causes the most damage on both sides. Deciding in advance what the household can give in total, and treating that as the budget, converts an open-ended commitment into a defined one. It also makes it possible to say yes to something specific rather than to an unbounded sequence.
The figure matters far less than the existence of one.
Label it accurately
A gift, a loan, and a stake in a property are three different arrangements with different consequences, and families routinely leave which one is intended unstated. Writing down what was intended, at the time, prevents a disagreement years later when memories diverge sincerely. Where money contributes toward a property, the arrangement may need to be documented formally to be recognised at all.
This is a case where legal advice is proportionate, particularly where a partner or a mortgage is involved.
Fairness between siblings
Help given to one child at one point, and not to another, is remembered, particularly after a parent dies. Some families equalise at the time; others record the amounts and adjust in the estate, which needs to be written into the will to have effect. Either approach works, and doing neither is what produces the disputes.
The conversation is easier while everyone is alive and much harder afterwards.
Non-financial support counts
Housing an adult child, providing childcare for grandchildren or covering a specific bill are all substantial help that does not deplete retirement provision as directly. For many households these are more sustainable than cash transfers and are valued similarly.
They carry their own costs in time, space and independence, which are worth being honest about rather than pretending are free. Being clear about the duration matters here as much as with money.
The takeaway
Decide the total you can give before the first request, and write down whether each transfer is a gift or a loan.
Small and repeatable beats ambitious and abandoned, almost every time.
Questions readers ask
Should I use retirement savings to help my child buy a home?
It is a real trade-off rather than an obvious answer, and money moved out of retirement provision late cannot be rebuilt. Anything substantial warrants regulated financial advice on your specific position.
How do I keep it fair between children?
Either equalise at the time or keep a record and reflect it in your will — and tell everyone which you are doing. Disputes almost always follow from arrangements nobody wrote down.