Family Costs
Two money histories, one household
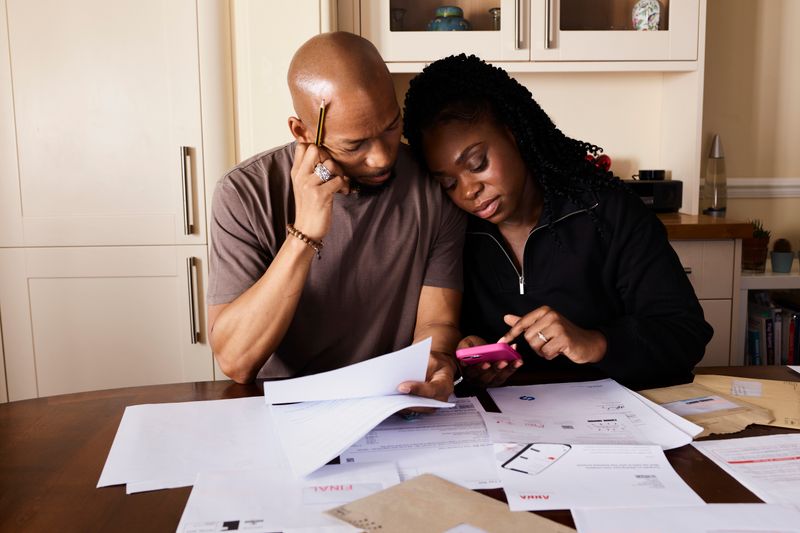
People arrive in a partnership with habits formed decades earlier by circumstances the other person never saw. Most money arguments are about that, not about the money.
This is written to be used rather than admired. Each section below is a decision about combining different money habits, and each one has a default.
Before you start
- Spending and saving instincts are largely formed by childhood financial circumstances.
- The same behaviour reads as reckless or as careful depending on the observer's history.
- Naming the history behind a habit defuses more arguments than any budgeting system.
Where the instincts come from
A person who grew up with unpredictable income tends to hold cash and distrust commitments; one who grew up with stability tends to be comfortable with debt and planning. Neither instinct is irrational, because both were adaptive in the circumstances that produced them. When two such people share a budget, the same decision looks obviously sensible to one and obviously alarming to the other.
Recognising the argument as a clash of histories rather than of judgement changes what can be resolved.
The conversation nobody has
Couples routinely discuss what they will spend and almost never discuss what money meant in the house each of them grew up in. Asking what your partner remembers about money as a child produces more insight in an hour than a year of budget discussions. It also converts what looked like stubbornness into something comprehensible and therefore negotiable.
The conversation is uncomfortable once and useful for decades.
Different does not mean incompatible
A cautious partner and a comfortable-with-risk partner frequently produce better decisions together than either would alone, provided both views are actually heard. The failure mode is one person controlling the decisions and the other disengaging, which removes the benefit and stores up resentment.
A structure where both people see the whole picture, even if one does the administration, preserves the check. Disengagement is also the state that leaves someone unable to manage if circumstances change suddenly.
Debt histories carry the most weight
Someone who has previously been in serious debt often carries a strong aversion that looks disproportionate from outside. Someone who has never experienced it may treat borrowing as a neutral tool, which it is until it is not. Being explicit about what each person has actually lived through changes how the household should set its own rules.
It also matters practically, since past difficulties can affect joint applications in ways worth discussing before applying.
Set rules, not verdicts
A threshold above which purchases get discussed, agreed independently, removes the need to relitigate each one. Where the threshold sits matters far less than the fact that both people chose it, which is what makes it hold.
Where it helps most, personal spending that requires no discussion at all is the other half of the same arrangement and is what keeps it survivable. Rules made in a calm week survive; rules imposed during an argument do not.
Revisit after every change
Arrangements agreed when both people earned similar amounts frequently become unfair when one takes a career break or a pay cut. Because the change is gradual, nobody renegotiates, and the arrangement quietly becomes a source of grievance.
In practice, a scheduled conversation, annually and after any income change, is unromantic and prevents most of it. What is being reviewed is the arrangement, not the person.
The takeaway
Ask your partner what money was like when they were ten. Most of the argument is in that answer.
Pick the one that costs you least, and let the rest wait.
Questions readers ask
How do we stop having the same argument about money?
Try having a different one: what money was like in each of your childhoods. Most repeated arguments are about a history the other person has never heard.
Should one person manage the household finances?
One person doing the administration is efficient. Both people seeing the full picture is what protects against disengagement and against being helpless if circumstances change.